
Dubai’s Rental Market in 2026 | What Actual Lease Transactions Reveal About Rents and Property Values
Dubai’s rental market is entering a more selective phase. Leasing activity remains substantial, but the relationship between advertised rents, actual tenancy agreements and property valuations is changing.
For landlords and investors, the distinction is increasingly important. A busy rental market does not necessarily mean rents are rising, and an attractive advertised rental yield does not always translate into an equally attractive investment return.
Rental registrations remain strong, but rents are adjusting
According to the Dubai Land Department (DLD), the first quarter of 2026 recorded 118,385 new rental contracts and 135,607 renewals, with a combined registered contract value of AED 32.2 billion.
These figures demonstrate the scale of Dubai’s rental market. However, contract registrations measure activity, not necessarily rental price growth.
More recent research reinforces that distinction.
Savills’ October 2026 residential market review reports a 16% quarterly recovery in rental transaction activity during Q3, following a weaker second quarter. Yet comparable new-lease rents declined year-on-year across several established residential communities.
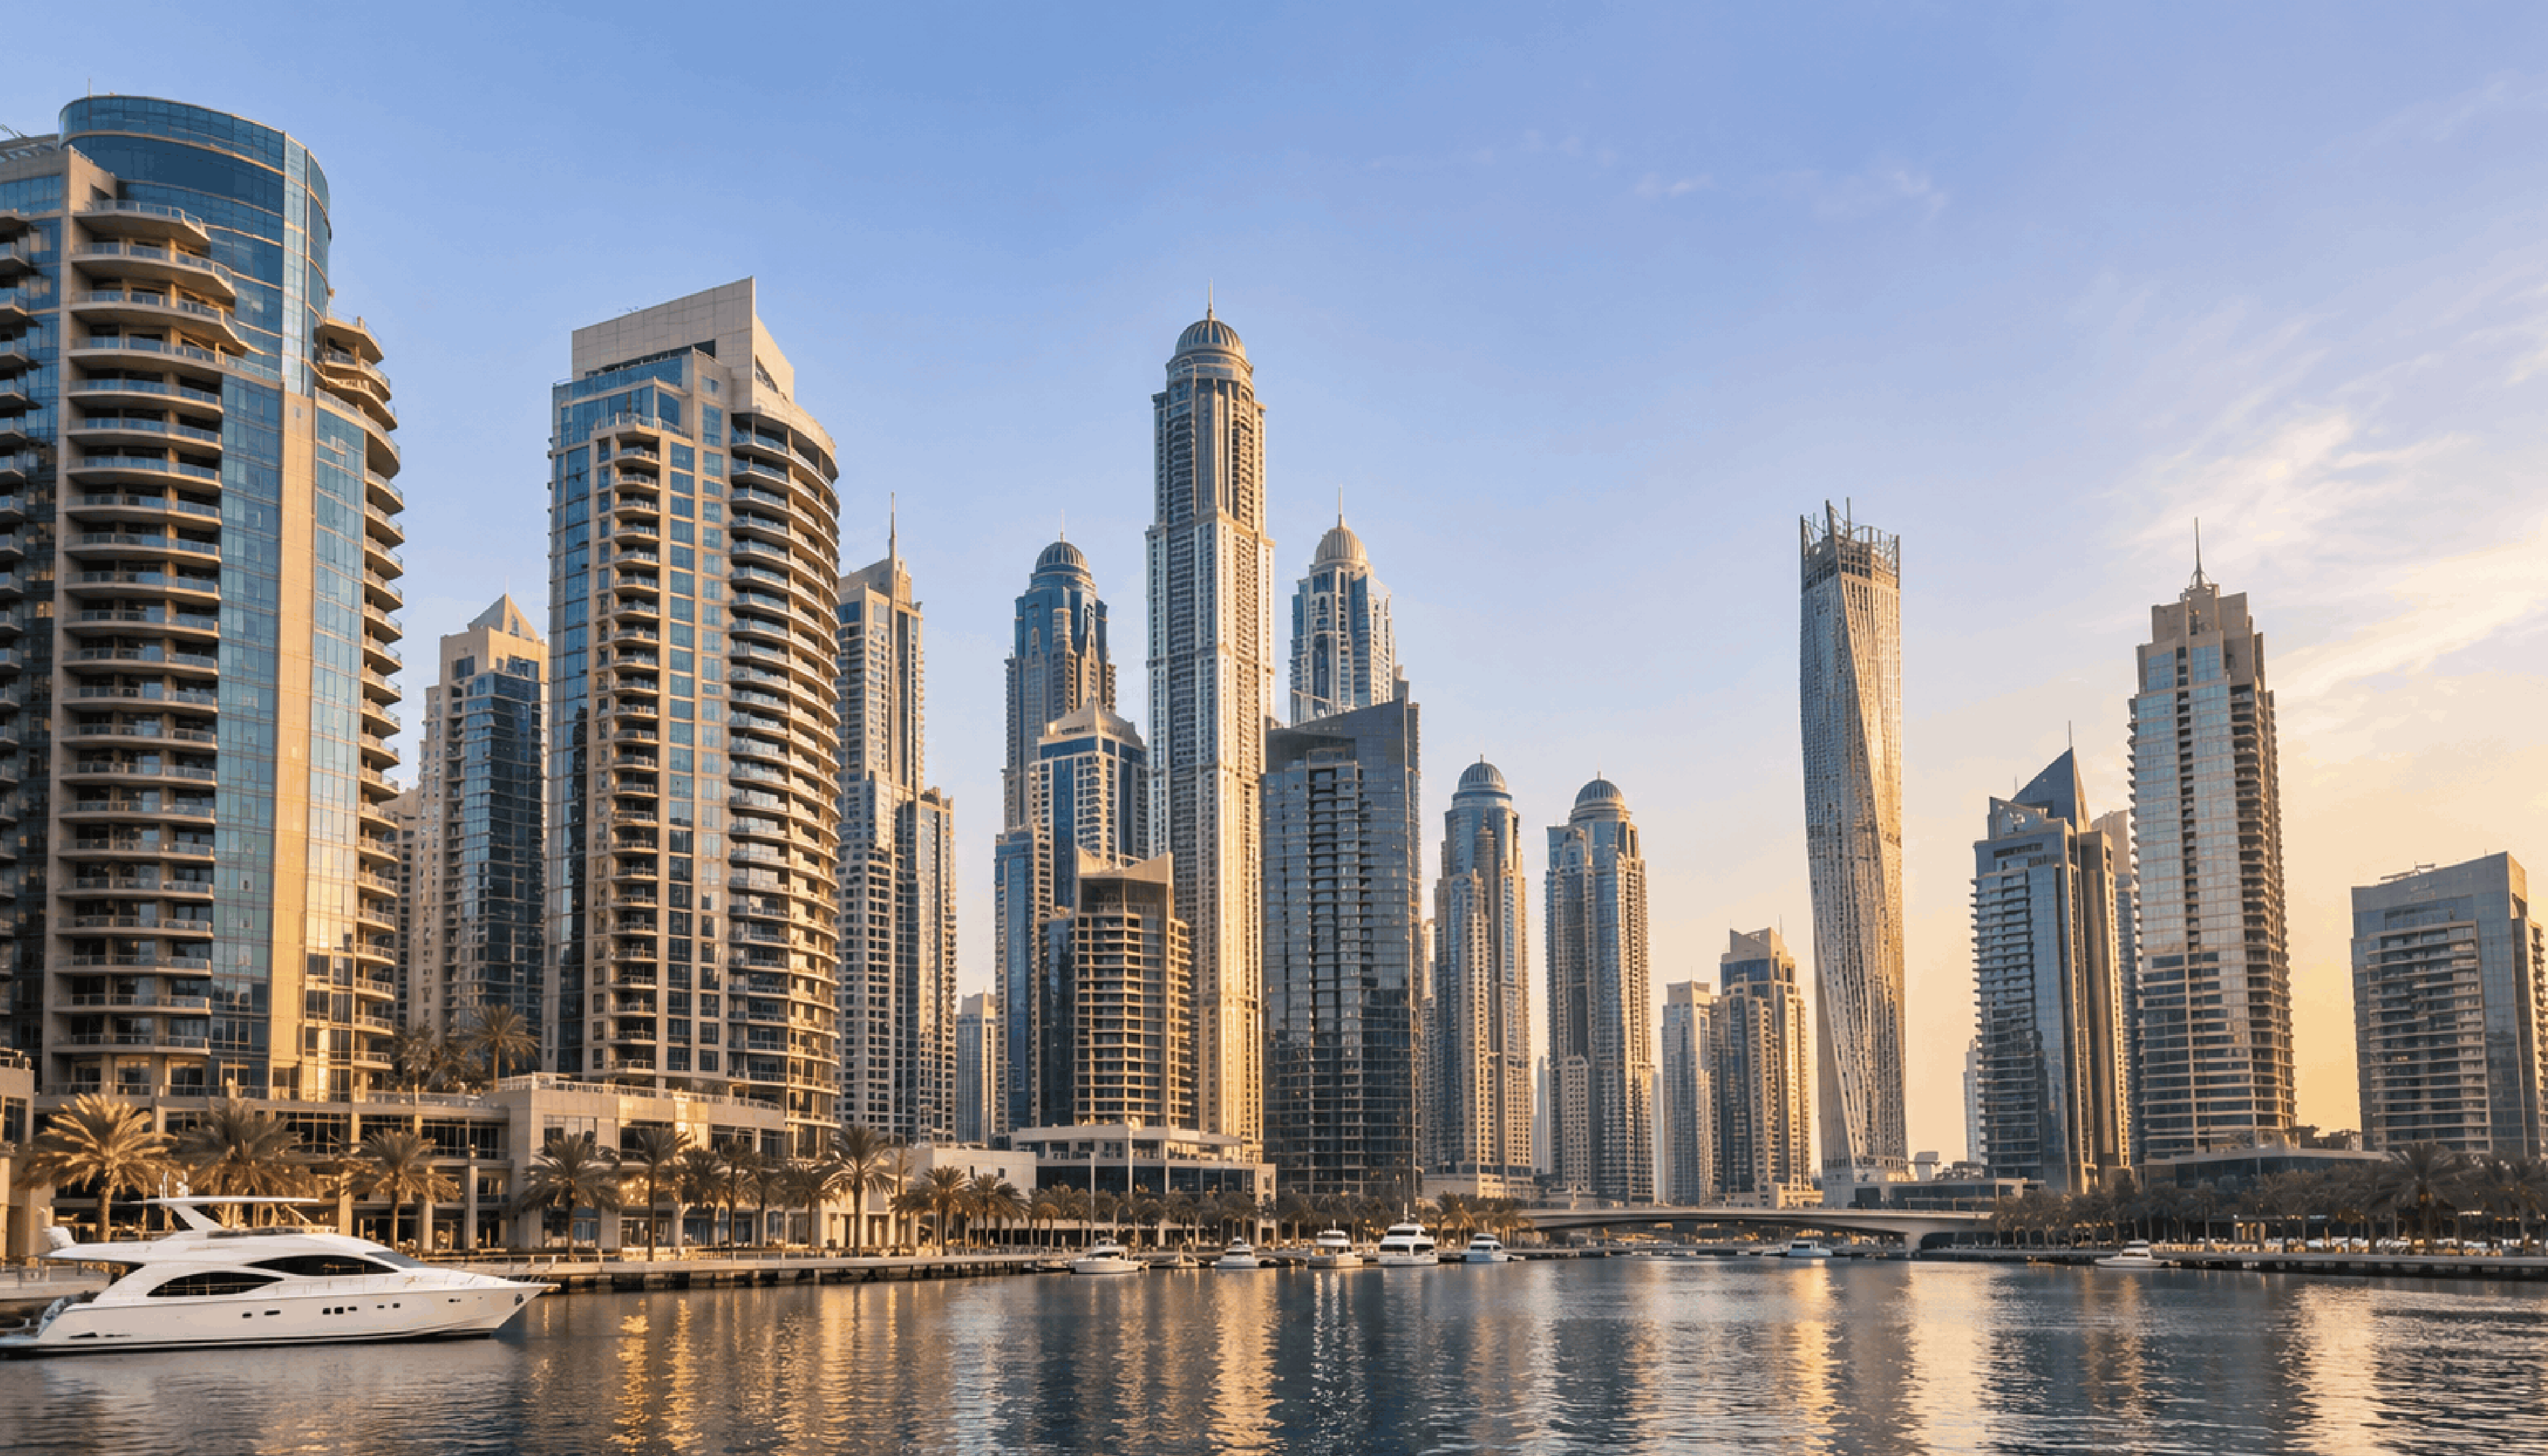
Dubai Marina, Business Bay and Jumeirah Village Circle were among the locations experiencing rental adjustments, while some villa and townhouse communities also recorded lower new-lease rents.
The picture is therefore more nuanced than either a booming or declining rental market. Tenants continue to sign leases, but landlords in certain locations are facing greater competition and more demanding price negotiations.
There are also early indications of stabilisation, with quarterly rental movements becoming less pronounced in several communities. Whether this develops into a sustained recovery will depend on demand, affordability and the pace of new supply.
Asking rents versus actual rental contracts: understanding the difference
One of the most important considerations when assessing Dubai’s rental market is the distinction between advertised asking rents and the amounts recorded in signed tenancy contracts.
Property portals primarily display what landlords are asking for available properties. These figures reflect expectations, positioning and prevailing competition, but do not necessarily represent the amounts tenants ultimately agree to pay.
DLD’s registered tenancy records provide a different perspective: the contractual rental amounts associated with completed registrations.
This distinction becomes particularly relevant when market conditions soften.
A landlord may advertise a property based on previous market peaks, competing listings or an anticipated negotiating margin. The final rental agreement may reflect concessions, a lower annual amount or different payment terms.
However, it would be misleading to suggest that all advertised properties are leased below their asking prices. The size and direction of any difference vary by location, property type, condition, availability and demand.
An equally important distinction exists between new tenancy agreements and renewals.
Renewal contracts may reflect longstanding tenant relationships and Dubai’s regulated rental-increase framework. Their registered values can therefore differ from the rents achievable on newly marketed vacant properties.
Consequently, comparing current advertised rents with the average of all registered contracts can produce misleading conclusions.
For investors, the most relevant evidence is the rent achieved on recent new leases for genuinely comparable properties, not simply the highest advertised rent in the same building.
This is particularly important when estimating future rental income or assessing whether an investment property’s asking price is justified.
Why rental income influences property values
Rental performance plays a significant role in determining the value of income-generating residential property.
Gross rental yield is calculated by dividing annual rental income by the property’s purchase price.
Consider an apartment valued at AED 2 million, generating AED 140,000 in annual rent. Its gross rental yield is 7%.
If the achievable annual rent declines to AED 126,000, the yield falls to 6.3%, assuming the property’s value remains unchanged.
To maintain a 7% gross yield at the lower rental income, an investor would need to acquire the property for approximately AED 1.8 million.
This illustration demonstrates the sensitivity of investment valuations to rental income.
It does not mean that a 10% decline in rents automatically causes a corresponding decline in property prices. Valuations also reflect expected capital appreciation, financing conditions, property scarcity, quality and longer-term rental prospects.
Nevertheless, sustained rental pressure can influence the prices investors are willing to pay, particularly in communities where rental income is a primary purchasing consideration.
The implications become more significant when future residential supply is taken into account.
Savills’ latest market outlook identifies a substantial pipeline of residential developments scheduled over the coming years. Although actual handovers may be delayed, additional completed homes will create greater competition in certain locations.
The result is likely to be a more differentiated market, where established communities, property quality, accessibility and competing supply increasingly influence both rental performance and resale values.
Dubai continues to offer competitive international rental yields
Despite these adjustments, Dubai remains an attractive market for income-oriented property investors.
According to the 2026 Dubai Investment Playbook published by haus & haus, Dubai’s average gross residential rental yield was approximately 6.76% in 2025.
The research also reported apartment gross yields of approximately 7.26% in June 2026, compared with 5.20% for villas.
These figures remain attractive when considered alongside indicative gross rental yields reported for several major international property markets, including prime London, Manhattan, Hong Kong and Singapore, where the cited benchmarks were generally lower.
International comparisons, however, require careful interpretation.
Property types, market boundaries, calculation methodologies and ownership costs differ between cities. A citywide Dubai apartment yield, for example, should not be treated as directly equivalent to the yield on prime London residential property.
More importantly, gross rental yields are not the same as net investment returns.
Investors must account for service charges, maintenance, vacancy periods, property management expenses, acquisition costs and, where relevant, financing expenses.
Dubai’s absence of a general personal income tax on residential rental income can also be advantageous, although an investor’s tax residency and individual circumstances may affect their ultimate tax obligations.
Dubai’s investment appeal therefore extends beyond headline rental yields. The more meaningful assessment is the sustainable net income a property can generate relative to its total acquisition and ownership costs.
A changing market calls for greater selectivity
The wider residential market provides additional context.
Savills’ October 2026 research describes a moderation in residential transaction activity, with reduced off-plan launches contributing to lower overall sales volumes.
However, the research also indicates that comparable-property prices have been considerably more resilient than headline transaction figures might suggest.
This is an important distinction.
Lower transaction volumes do not automatically imply an equivalent decline in property values, just as strong rental registrations do not necessarily indicate increasing rents.
Both markets are becoming more selective.
For landlords, realistic rental pricing is increasingly important to minimise vacancy and attract qualified tenants.
For buyers, attention should shift from projected rental returns to evidence of achievable income.
For existing investors, the focus should be on protecting net returns through effective property management, sensible pricing and an understanding of competing supply.
And for sellers, valuations need to reflect current buyer expectations rather than relying exclusively on historical price growth or advertised comparable properties.
Looking beyond the headlines
Dubai continues to benefit from an established investment environment, an active residential leasing market and internationally competitive gross rental yields.
However, the market is evolving.
Rental growth is no longer uniform, tenants have greater negotiating power in certain communities, and future residential supply may create further differences in performance between locations and individual properties.
These developments do not diminish Dubai’s long-term investment appeal. They reinforce the importance of disciplined analysis.
At DEVOSHN Real Estate, we believe informed property decisions should be based on actual market transactions, realistic rental expectations and a clear assessment of risk and return.
Whether acquiring, leasing, holding or selling property, understanding the fundamentals behind the numbers is essential to protecting long-term value.
Disclaimer: This article provides general market commentary based on publicly available information and independent analysis. Market conditions and investment returns vary by property. Illustrative calculations are not forecasts or guarantees of future performance.